What is MAT and how to calculate it? MAT, or Minimum Alternate Tax, is a provision in India that requires businesses to pay a minimum amount of tax, even if they employ deductions and exclusions to reduce their taxable revenue to zero or a very small amount. This provision was enacted to discourage firms from dodging taxes despite making large profits.
Section 115JB ensures that companies pay a minimum amount of tax even if they use deductions and exemptions to reduce their taxable income. This prevents companies from paying little or no tax despite having high book profits.
Who Needs to Pay MAT?
All companies, including Indian and foreign companies with a presence in India, must pay MAT if their regular tax is lower than the calculated MAT.
How is MAT Calculated?
A company must pay the higher of the following two amounts:
1. Normal Income Tax (Tax calculated as per regular income tax provisions).
2. MAT = 15% of “Book Profit” + Surcharge + Cess.
Book profit is calculated based on the company’s profit and loss account after making adjustments as per the law.
Example Calculation of MAT
Let’s assume a company has the following details for the financial year 2026-27:
Book Profit: ₹10 Crore
Normal Tax Calculation: ₹1.5 Crore
Step 1: Calculate MAT
MAT = 14% of Book Profit + 4% Health & Education Cess
MAT = (₹10 Crore × 14%) + 4% of (₹1.4 Crore)
= ₹1.4 Crore + ₹0.056 Crore
= ₹1.456 Crore
Step 2: Compare with Normal Tax
Normal Tax: ₹1.5 Crore
MAT: ₹1.456 Crore
Since MAT (₹1.456 Crore) is higher than Normal Tax (₹1.5 Crore), the company must pay ₹1.456 Crore as tax.
What Happens to the Extra Tax Paid Under MAT? (MAT Credit)
If a company pays more tax under MAT than normal tax, the extra tax is called MAT Credit.
MAT Credit can be carried forward for 15 years and used when the company’s normal tax is higher than MAT in the future.
Example of MAT Credit Usage
In the next financial year (2025-26), if:Normal Tax: ₹3 Crore
MAT: ₹2 Crore
Since normal tax is now higher than MAT, the company can use its MAT Credit of ₹0.06 Crore (₹1.56 Crore – ₹1.5 Crore from the previous year) to reduce its tax liability.
New Tax Payable = ₹3 Crore – ₹0.06 Crore = ₹2.94 Crore.
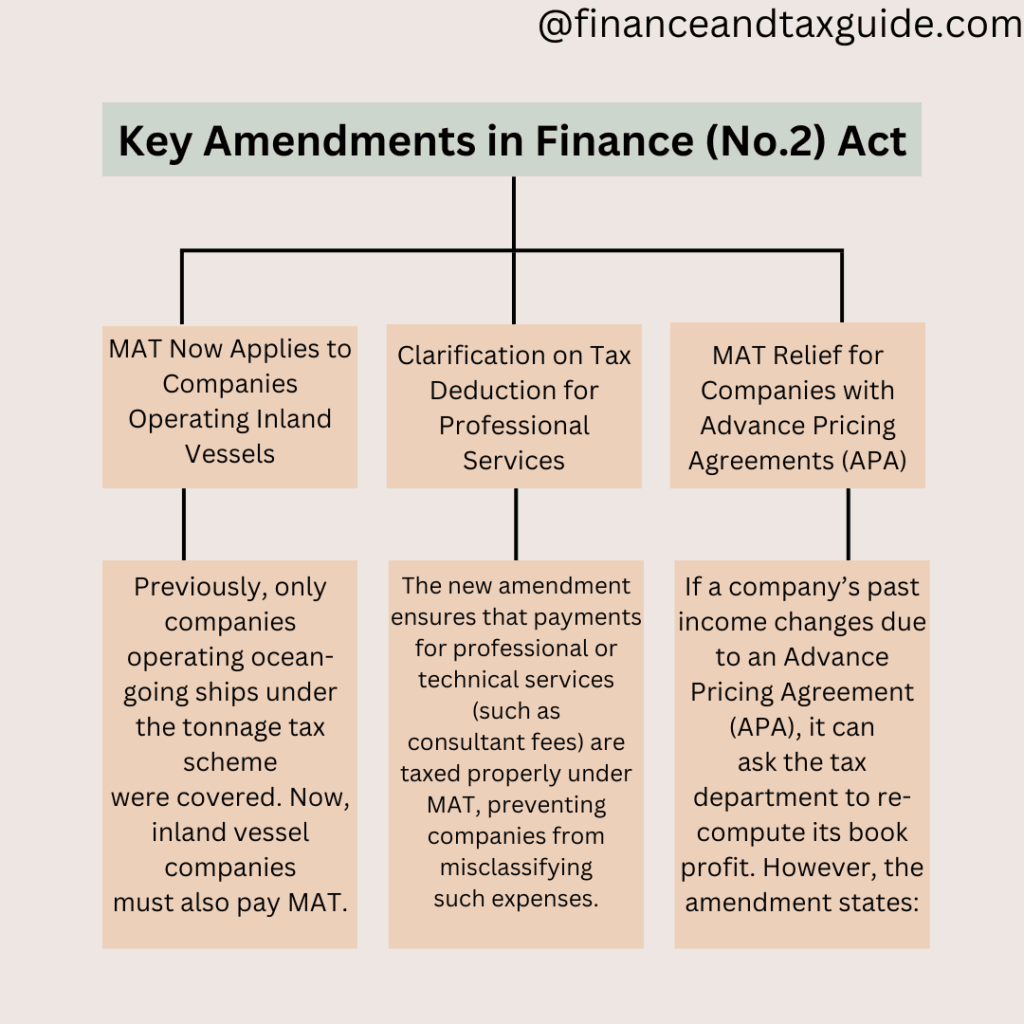
Key Amendments in Finance (No.2) Act, 2024
1. MAT Now Applies to Companies Operating Inland Vessels
Previously, only companies operating ocean-going ships under the tonnage tax scheme were covered. Now, inland vessel companies (boats, ferries, barges used in rivers/lakes) must also pay MAT.
2. Clarification on Tax Deduction for Professional Services
The new amendment ensures that payments for professional or technical services (such as consultant fees) are taxed properly under MAT, preventing companies from misclassifying such expenses.
3. MAT Relief for Companies with Advance Pricing Agreements (APA)
If a company’s past income changes due to an Advance Pricing Agreement (APA), it can ask the tax department to re-compute its book profit. However, the amendment states:
If a company already used MAT credit, they cannot claim an adjustment.
No interest refund will be given if MAT tax is reduced due to re-computation.
Conclusion
Section 115JB ensures fair taxation by making companies pay a minimum tax of 18.5% of book profit. The 2024 amendments clarify tax rules for shipping, professional services, and past income adjustments. Companies should review these changes to plan their taxes effectively.

He founded Finance and Tax Guide to simplify complex tax and accounting topics for Indian small businesses, entrepreneurs, and individual taxpayers.
His expertise includes:
• GST Registration and Return Filing
• Income Tax Return (ITR) Filing
• TDS and TCS Compliance
• Business Bookkeeping
• Financial Accounting
• Tax Planning for Small Businesses
Every article published on Finance and Tax Guideis based on practical accounting experience and current Indian tax laws to provide accurate,
easy-to-understand financial guidance.